
ECLGS 5.0 Explained: ₹2.55 Lakh Crore Credit Guarantee Push
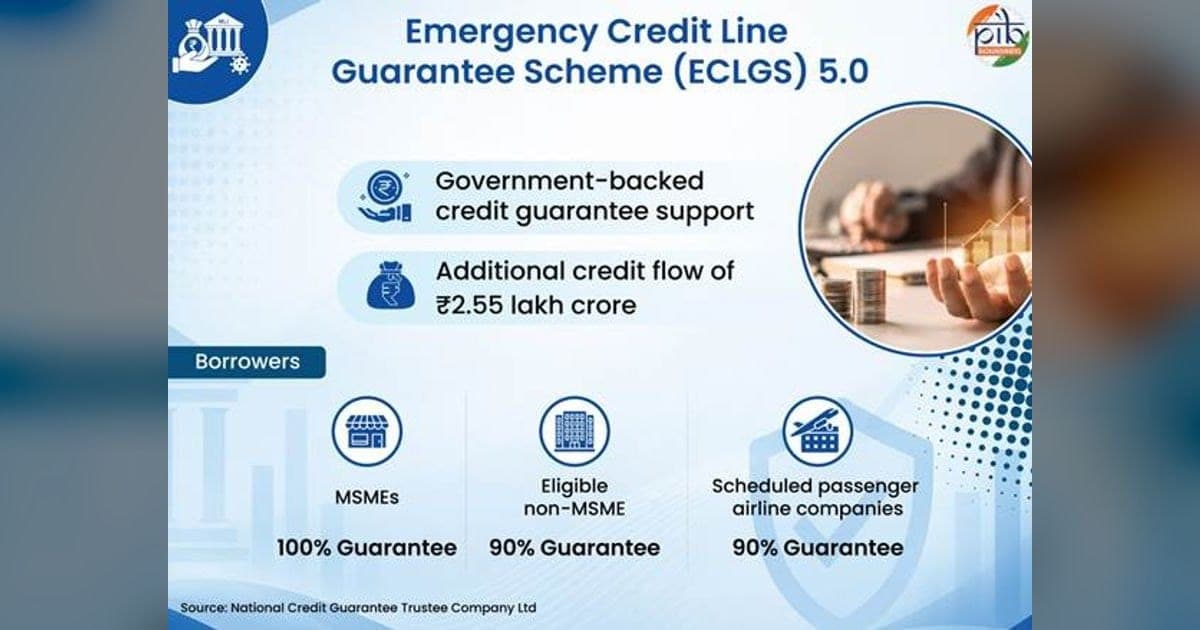
ECLGS 5.0, approved on 5 May 2026 and run by NCGTC, targets an extra credit flow of ₹2.55 lakh crore for MSMEs, non-MSMEs and scheduled passenger airlines.
Why in News
On 5 September 2026 PIB issued a backgrounder on ECLGS 5.0, the credit guarantee scheme approved on 5 May 2026 to push up to ₹2.55 lakh crore of additional working capital credit to MSMEs, non-MSMEs and scheduled passenger airlines.
PIB issued a backgrounder on the Emergency Credit Line Guarantee Scheme (ECLGS) 5.0 on 5 September 2026. The scheme gives government-backed credit guarantees to lenders so that they can hand businesses extra working capital at lower risk. The Government approved it on 5 May 2026. It is implemented by the National Credit Guarantee Trustee Company (NCGTC). The target is an additional credit flow of up to ₹2.55 lakh crore.
Who the scheme covers
Three groups are covered. The first is MSMEs, across all sectors. The second is eligible non-MSME business borrowers, with some sectors left out. The third is scheduled passenger airline companies. Credit reaches them through scheduled commercial banks, scheduled urban co-operative banks, financial institutions and eligible NBFCs, which the scheme calls Member Lending Institutions.
The terms for MSMEs and non-MSMEs
A borrower must already have working capital facilities from a lender as on 31 March 2026, and repayments must not be overdue by more than 60 days. The guarantee cover is 100 per cent for eligible MSMEs and 90 per cent for eligible non-MSMEs, and no guarantee fee is charged to lenders. Extra credit is capped at 20 per cent of the peak fund-based working capital outstanding in the fourth quarter of 2025-26, subject to a ceiling of ₹100 crore per borrower. Interest for MSMEs is linked to EBLR and for non-MSMEs to MCLR, with lenders allowed up to 0.75 per cent above the benchmark and an overall cap of 9 per cent a year. For eligible NBFCs the rate cannot cross 13 per cent a year. The loan runs 5 years including a 1-year moratorium.
The terms for airlines
A scheduled passenger airline qualifies if it held fund-based and non-fund-based credit facilities as on 31 March 2026, classified as Standard on that date. The guarantee cover is 90 per cent. Extra credit can go up to 100 per cent, with a ceiling of ₹1,500 crore per borrower. Anything above ₹1,000 crore needs a matching equity contribution from the promoters. The loan runs 7 years with a 2-year moratorium.
Where the scheme has reached
| As on 20 August 2026 | Figure |
| Guarantees issued | 6,73,979 |
| Guaranteed amount | ₹2,50,024 crore |
| MSME share by number | 97.3 per cent |
| MSME share by amount | 80.79 per cent |
| Scheme valid till | 31 March 2027, or till ₹2.55 lakh crore of guarantees |
The earlier phases
ECLGS was launched in 2020 under the Aatmanirbhar Bharat Package to pull businesses through the pandemic. ECLGS 1.0 covered MSMEs, business enterprises, Mudra borrowers and individual business loans. ECLGS 2.0 took in 26 stressed sectors identified by the Kamath Committee and the healthcare sector. ECLGS 3.0 covered hospitality, travel and tourism, leisure and sporting, and civil aviation. ECLGS 4.0 went to hospitals, nursing homes, clinics, medical colleges and makers of liquid oxygen and oxygen cylinders. From 1.0 to 4.0 the phases issued 1.19 crore guarantees worth ₹3.68 lakh crore and ended on 31 March 2023. Applications under the current phase are filed through the Jan Samarth Portal.
Important Facts
| Scheme | Emergency Credit Line Guarantee Scheme (ECLGS) 5.0 |
|---|---|
| Approved on | 5 May 2026 |
| Implemented by | National Credit Guarantee Trustee Company (NCGTC) |
| Target credit flow | Up to ₹2.55 lakh crore |
| Valid till | 31 March 2027, or till guarantees of ₹2.55 lakh crore are issued |
| Guarantee cover | 100 per cent for MSMEs, 90 per cent for non-MSMEs and airlines |
| Ceiling per borrower | ₹100 crore for MSMEs and non-MSMEs, ₹1,500 crore for airlines |
| Interest cap | 9 per cent a year for banks, 13 per cent a year for eligible NBFCs |
| Progress as on 20 August 2026 | 6,73,979 guarantees worth ₹2,50,024 crore |
| Application route | Jan Samarth Portal |
| Earlier phases | ECLGS 1.0 to 4.0 issued 1.19 crore guarantees worth ₹3.68 lakh crore and closed on 31 March 2023 |
Exam Point of View
Remember the outlay of ₹2.55 lakh crore, the implementing agency NCGTC, the approval date of 5 May 2026 and the validity till 31 March 2027, the guarantee cover of 100 per cent for MSMEs and 90 per cent for others, the per-borrower ceilings of ₹100 crore and ₹1,500 crore, and the Jan Samarth Portal.
Practice Questions
What is the additional credit flow that ECLGS 5.0 aims to facilitate?
- A.₹1.50 lakh crore
- B.₹2.55 lakh crore
- C.₹3.68 lakh crore
- D.₹5 lakh crore
Show answer
Correct answer: B. ₹2.55 lakh crore
Explanation
The correct answer is ₹2.55 lakh crore. The backgrounder states that the scheme, approved on 5 May 2026 and implemented by the National Credit Guarantee Trustee Company, aims to facilitate an additional credit flow of up to that amount, and that the scheme runs till 31 March 2027 or till guarantees of the same value are issued, whichever comes earlier. Option C is the trap here, because ₹3.68 lakh crore is a real figure from the same release, but it belongs to the earlier phases: from ECLGS 1.0 to 4.0 the scheme issued 1.19 crore guarantees worth ₹3.68 lakh crore before closing on 31 March 2023. Options A and D are round figures with no support in the release. Keep the two numbers in separate lines while revising: ₹2.55 lakh crore is the target of the present phase, and ₹3.68 lakh crore is what the first four phases actually delivered. The progress figure for the present phase, as on 20 August 2026, was ₹2,50,024 crore of guarantees.
Under ECLGS 5.0, what is the credit guarantee cover for loans extended to eligible MSMEs?
- A.75 per cent
- B.80 per cent
- C.90 per cent
- D.100 per cent
Show answer
Correct answer: D. 100 per cent
Explanation
The correct answer is 100 per cent. The release separates the two levels of cover clearly: eligible MSMEs get a full guarantee, while eligible non-MSME borrowers get 90 per cent cover. The same 90 per cent applies to loans given to eligible scheduled passenger airlines. Option C is therefore the most tempting wrong answer, because 90 per cent is a genuine figure from the scheme but belongs to the other categories of borrower. Options A and B appear nowhere in the release. Two more points are worth carrying along with this item. First, no guarantee fee is payable by the Member Lending Institutions under the scheme. Second, the cover was 100 per cent in the original ECLGS launched in 2020 under the Aatmanirbhar Bharat Package as well, so the full cover for small borrowers is a continuing feature of the scheme rather than something new. Additional credit for MSMEs is capped at 20 per cent of peak working capital outstanding, subject to ₹100 crore per borrower.
Which agency implements the Emergency Credit Line Guarantee Scheme 5.0?
- A.Reserve Bank of India
- B.Small Industries Development Bank of India
- C.National Credit Guarantee Trustee Company
- D.National Bank for Agriculture and Rural Development
Show answer
Correct answer: C. National Credit Guarantee Trustee Company
Explanation
The correct answer is the National Credit Guarantee Trustee Company, usually written as NCGTC. The backgrounder names it as the implementing agency and adds that borrowers must satisfy the eligibility conditions prescribed by NCGTC, including account status and other lending norms. Option A is the most attractive distractor, because the Reserve Bank of India does appear in the release, but only in the explanation of the benchmarks: EBLR and MCLR are the rates tied to the central bank, and MSME loans under the scheme are priced off EBLR while non-MSME loans are priced off MCLR. Options B and D name development finance institutions that run their own refinance and guarantee programmes for small industry and for agriculture, which is why they look plausible, but neither of them implements this scheme. Remember the chain of delivery: NCGTC gives the guarantee, Member Lending Institutions give the loan, and the borrower applies through the Jan Samarth Portal.
Frequently Asked Questions
What is the target of ECLGS 5.0 and who runs it?
The scheme aims to facilitate an additional credit flow of up to ₹2.55 lakh crore. It is implemented by the National Credit Guarantee Trustee Company, and the Government approved it on 5 May 2026.
How much guarantee cover does an MSME borrower get?
Loans to eligible MSMEs carry a 100 per cent guarantee. Eligible non-MSME borrowers and scheduled passenger airlines carry 90 per cent cover, and lenders pay no guarantee fee.
How much credit has the scheme guaranteed so far?
As on 20 August 2026, 6,73,979 guarantees worth ₹2,50,024 crore had been issued. MSMEs made up 97.3 per cent of the guarantees by number and 80.79 per cent by amount.
Where does a borrower apply?
Through the Jan Samarth Portal. The scheme stays open till 31 March 2027, or till guarantees of ₹2.55 lakh crore are issued, whichever comes first.
Sources
- Emergency Credit Line Guarantee Scheme (ECLGS) 5.0 (opens in a new tab) — Press Information Bureau
Current Affairs 5 September 2026
- National Teachers Awards 2026: President Honours 82 TeachersAwards & Honours
- Indore Metro Priority Corridor-2 Opens with 11 StationsState News
- NBA Crosses ₹200 Crore in Access and Benefit-Sharing PayoutsEnvironment
- Coal Gasification Scheme: ₹37,500 Crore Outlay, NTPC AppliesGovernment Schemes
- Vice President Launches India Valve Registry in ChennaiScience & Technology
- Commemorative Stamp Marks 75 Years of Dinamalar NewspaperNational
Related Current Affairs
- Banking & Finance
GIFT IFSC Banks Disburse $52.82 Billion Under RBI Swap Facility
23 September 2026 · 2 min read
- Banking & Finance
Bankers' Books Evidence Act 2026 in Force from 1 October
23 September 2026 · 2 min read
- Banking & Finance
IPPB Marks 9th Foundation Day, Launches DakPay Sound Box
23 September 2026 · 2 min read
- Banking & Finance
Government Urges PSB and RRB Staff to Call Off Bank Strikes
22 September 2026 · 2 min read
Related GK
- Fundamental Rights (Articles 12–35): Notes, Writs and PYQs
23 September 2026 · Indian Polity
- Preamble of the Indian Constitution: Notes, Keywords and PYQs
22 September 2026 · Indian Polity
- Making of the Indian Constitution: Notes, Key Dates and PYQs
21 September 2026 · Indian Polity
Take the Quiz
- Current Affairs Quiz
State Exams Current Affairs Quiz: 5 September 2026
21 questions21 minutesStart Quiz